TFS funding
Get Your Credit Ready For Your Next Property.
Your credit profile shouldn't stand between you and your next financial opportunity. Discover what may be holding you back and take the first step toward a stronger financial future.
Personalized Strategy
Confidential
No Obligation
What's Holding You Back?
Stop Guessing. Start Moving Forward.
Credit Holding You Back
Worried your current credit profile is preventing you from reaching your property or funding goals?
Negative Items
Understand the negative or inaccurate information that may be affecting your overall profile.
High Utilization
High balances can impact how your credit profile is viewed. Know what needs attention.
No Clear Direction
Instead of trying random fixes, understand what steps make sense for your situation.
Your Next Opportunity
Work toward a stronger profile and a clearer path toward your financial and real estate goals.
Know where you stand. Know what to work on. Know your next move.
Take The Next Step
Let's Talk About Your Goals.
Complete the application to tell us a little about your current credit profile and what you're working toward.
Take The Next Step
Let's Talk About Your Goals.
Complete the application to tell us a little about your current credit profile and what you're working toward.
Take The Next Step
Let's Talk About Your Goals.
Complete the application to tell us a little about your current credit profile and what you're working toward.
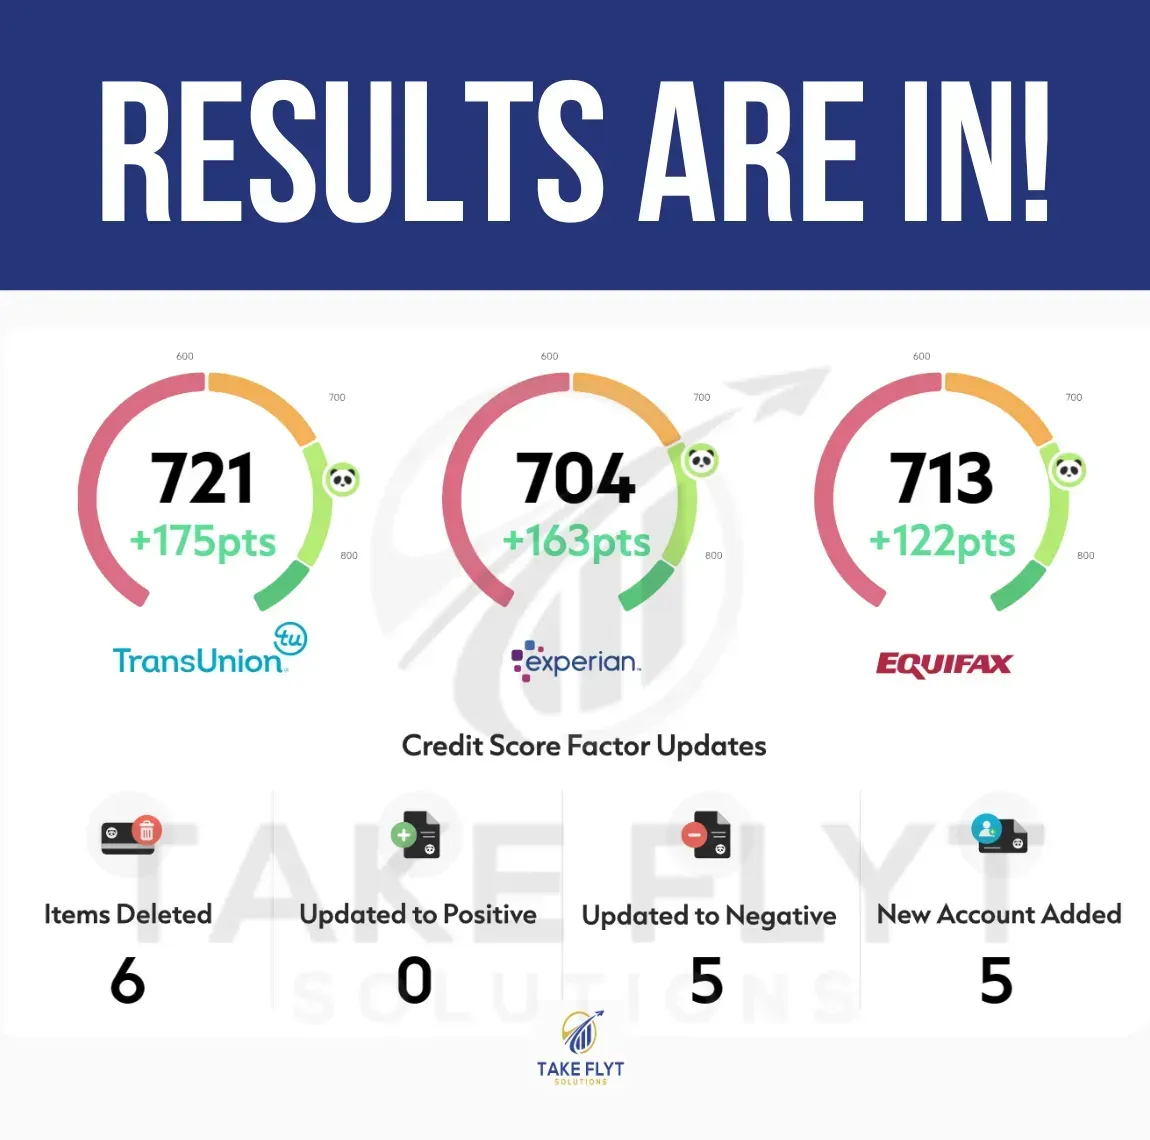
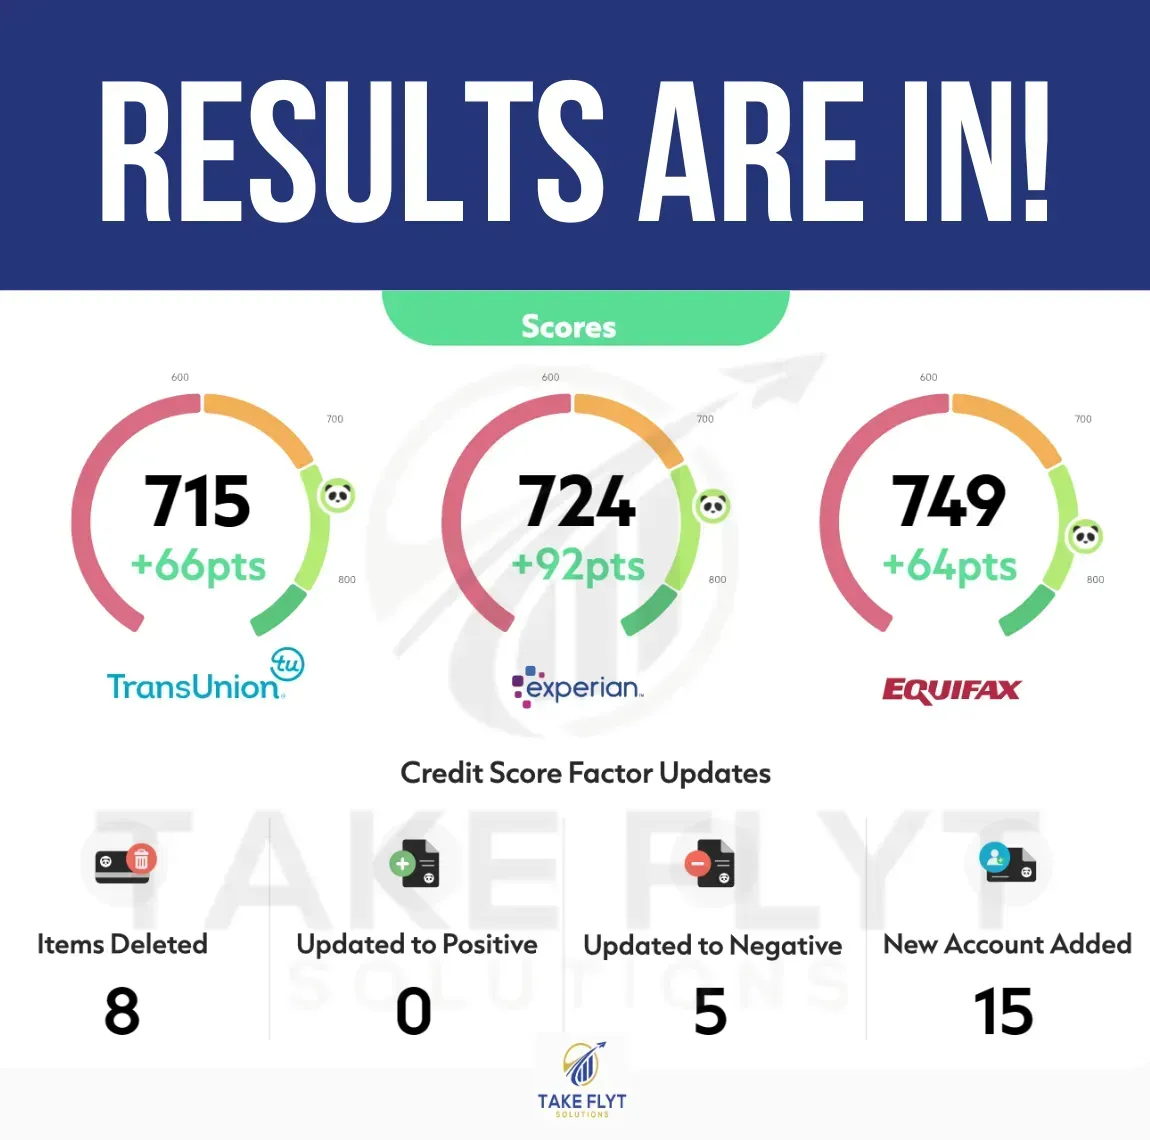
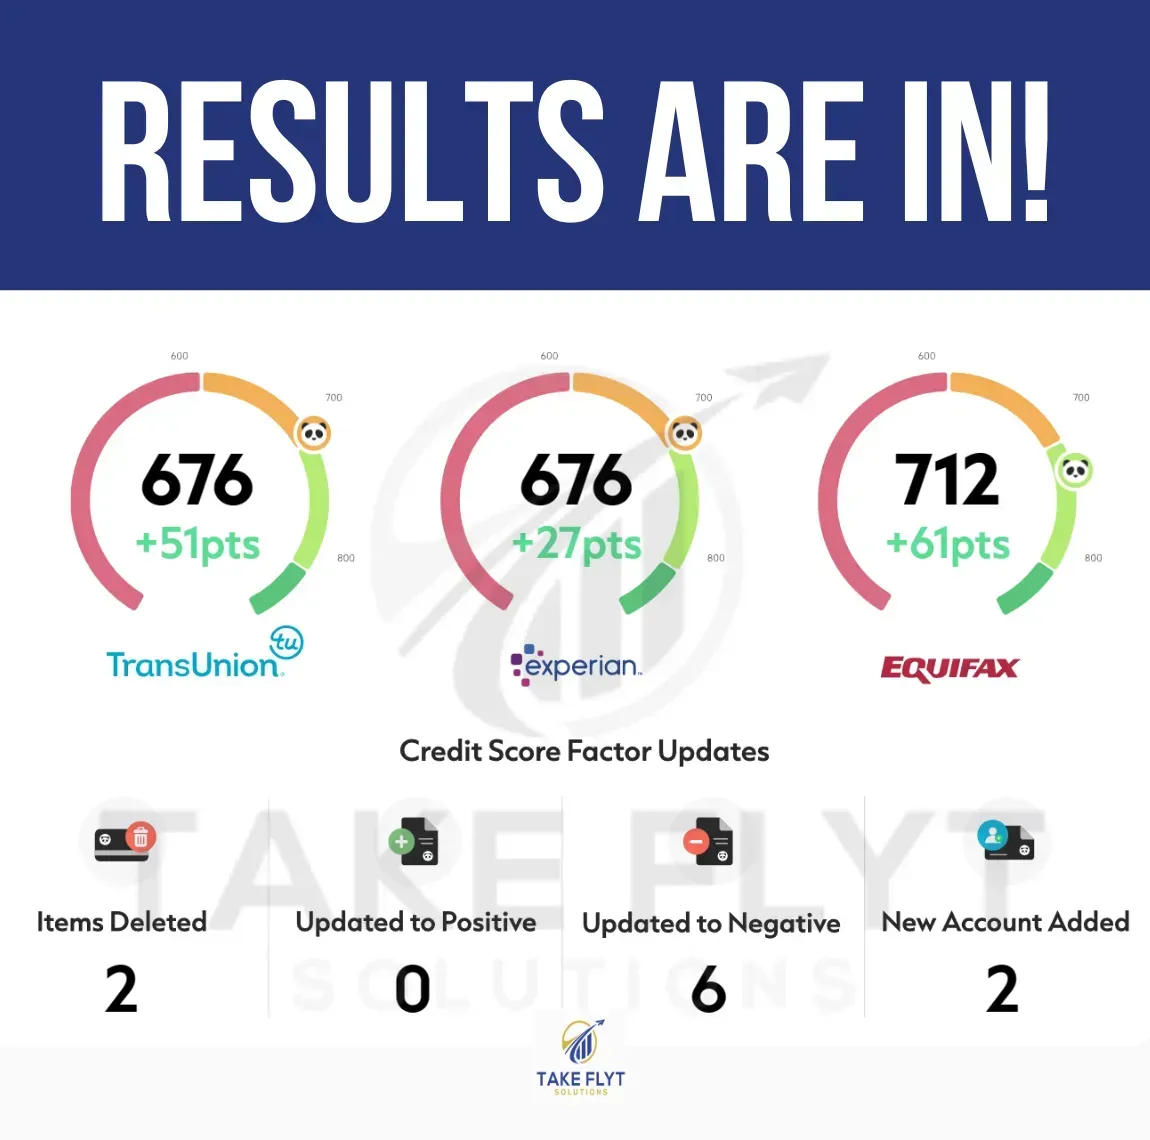
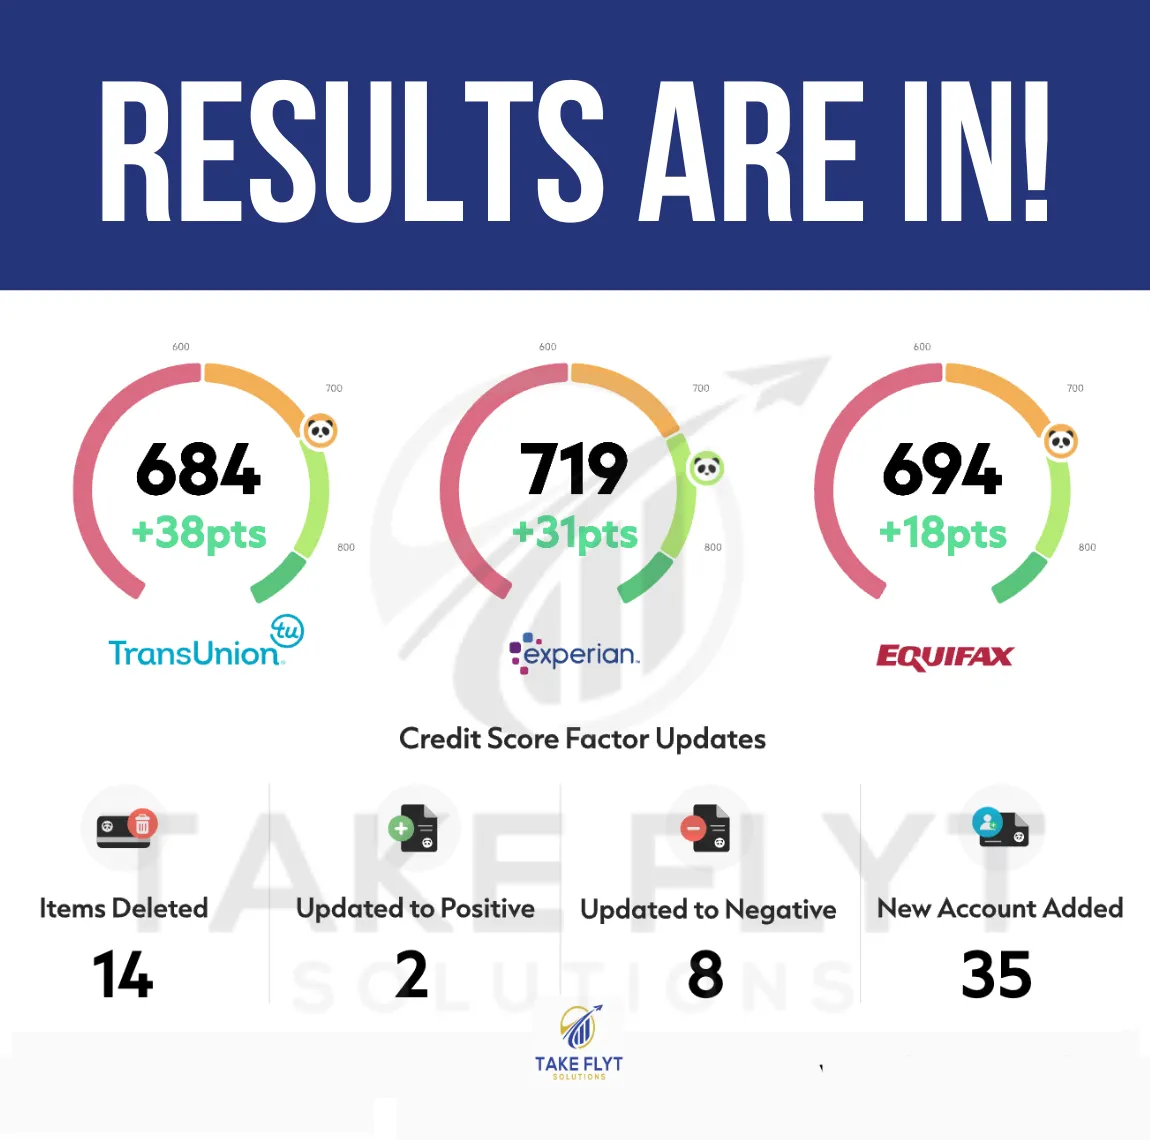
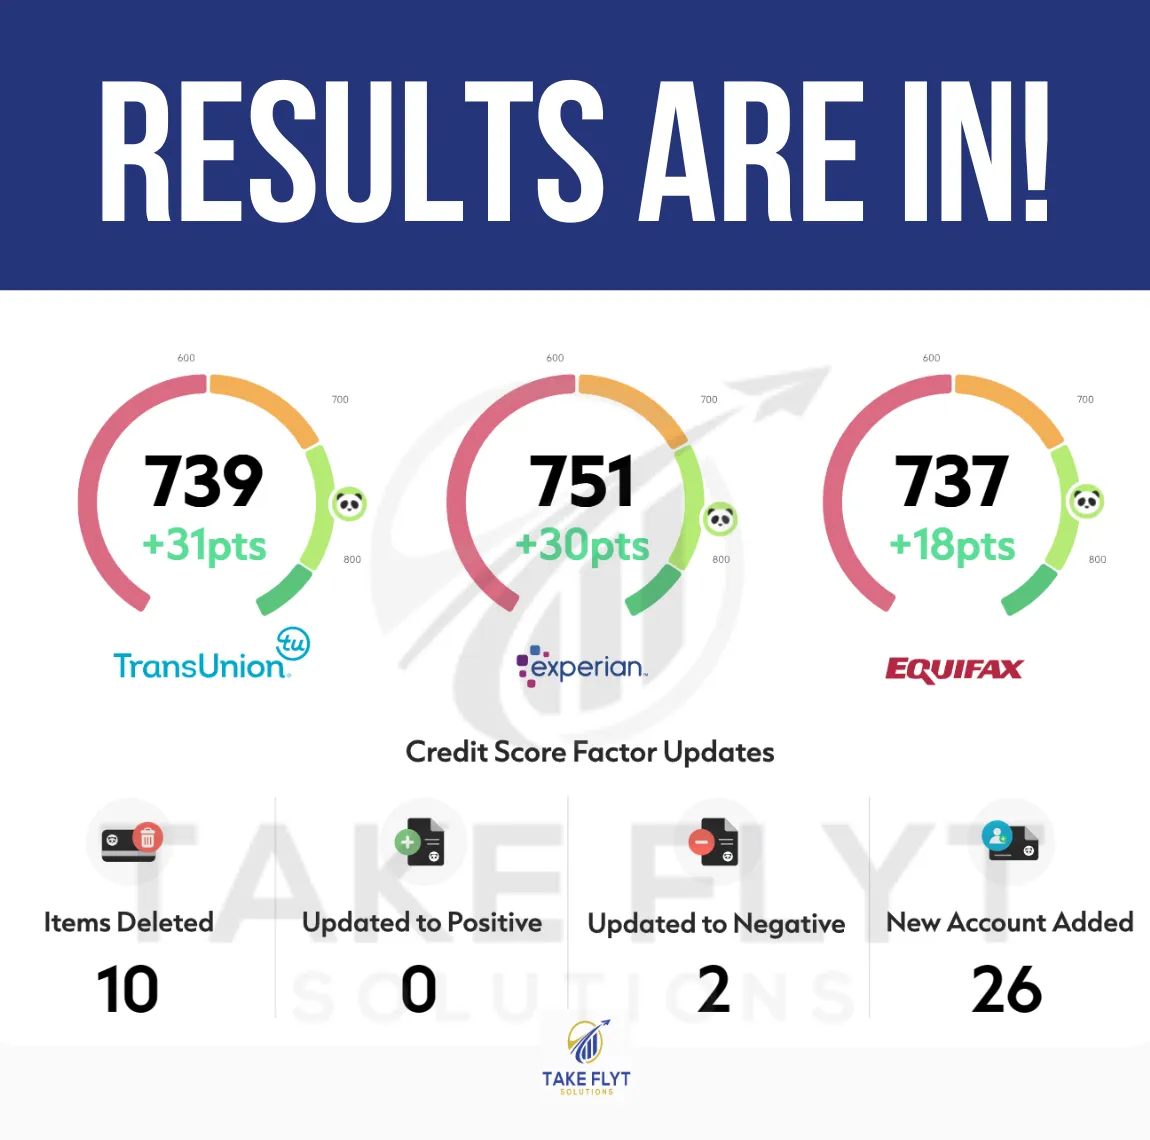
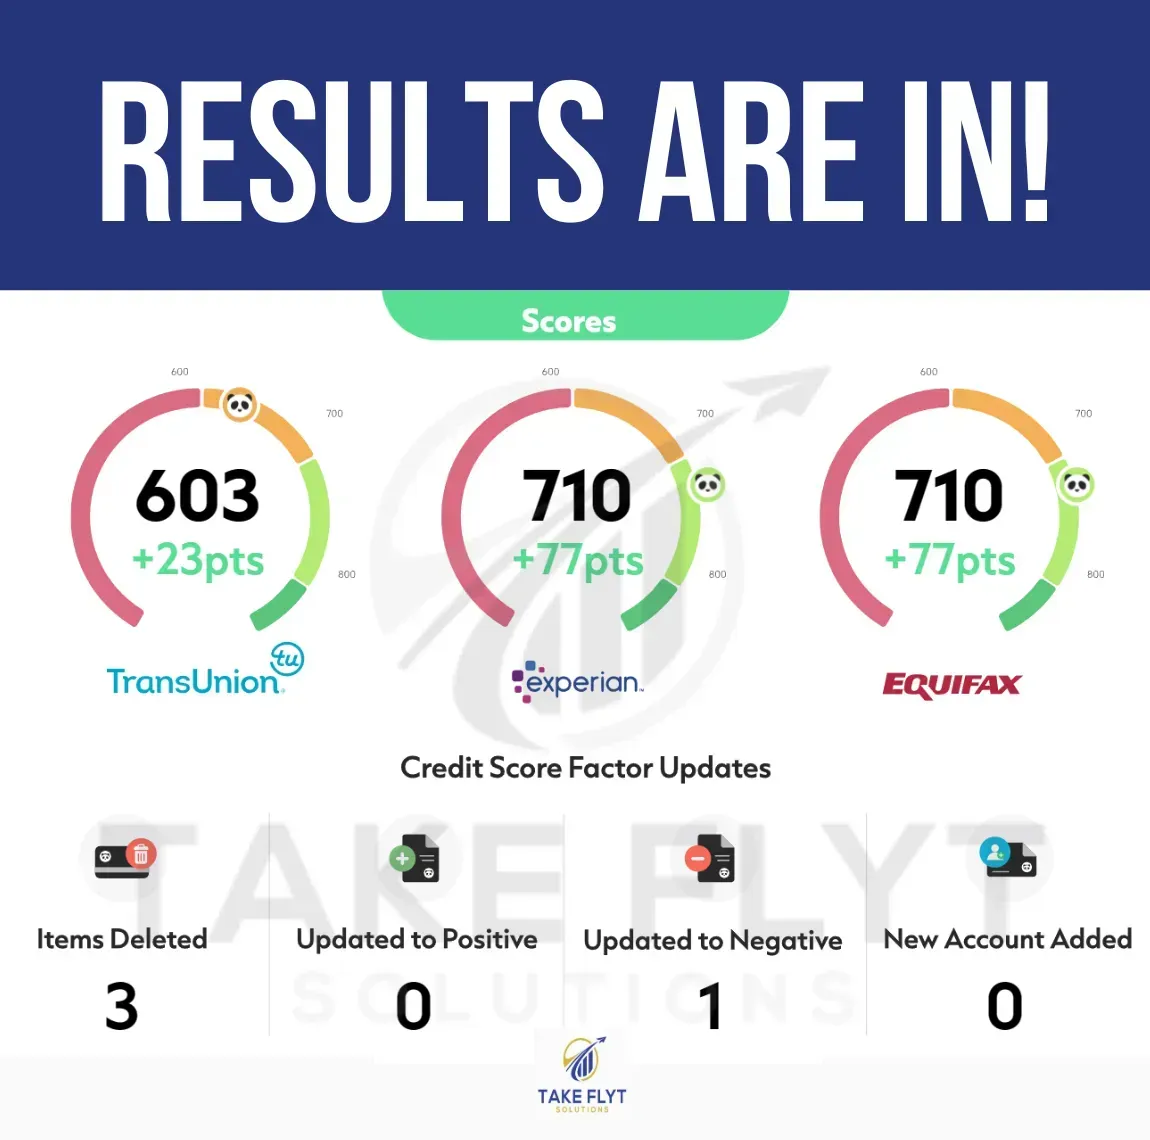
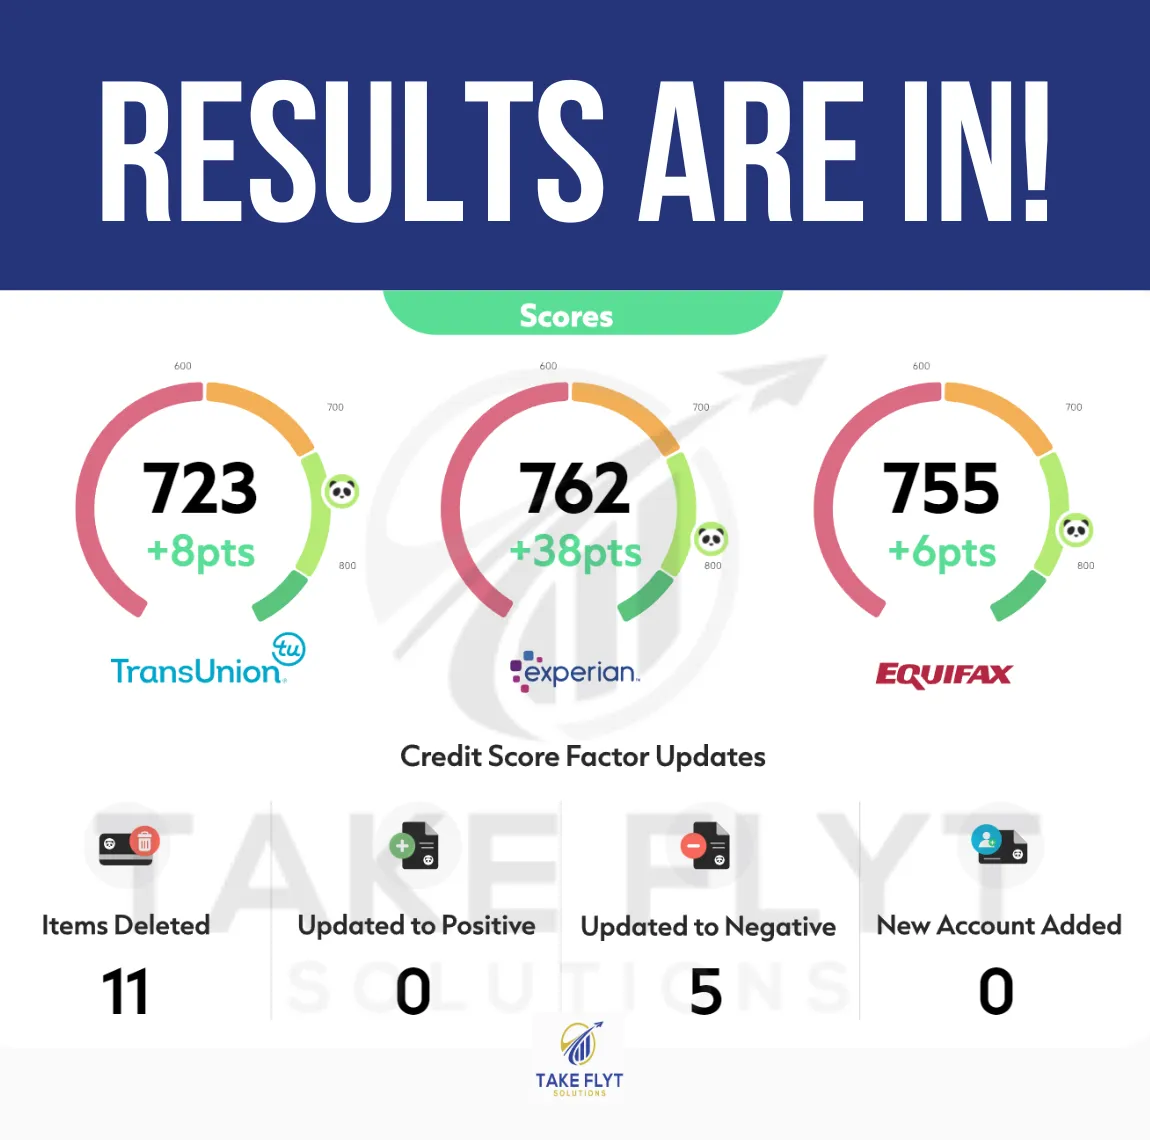
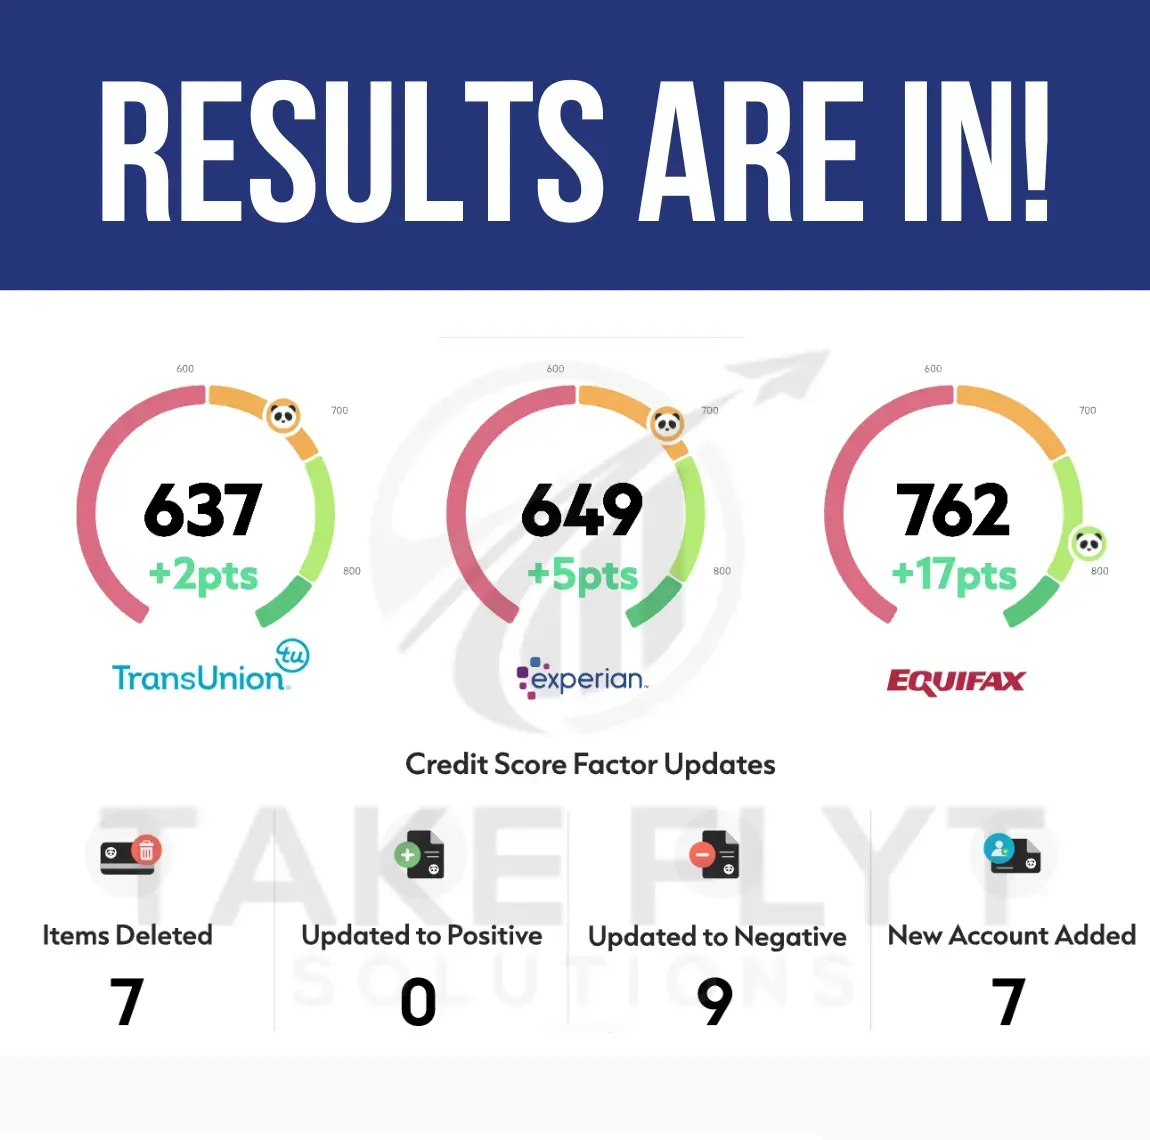
Client Proof
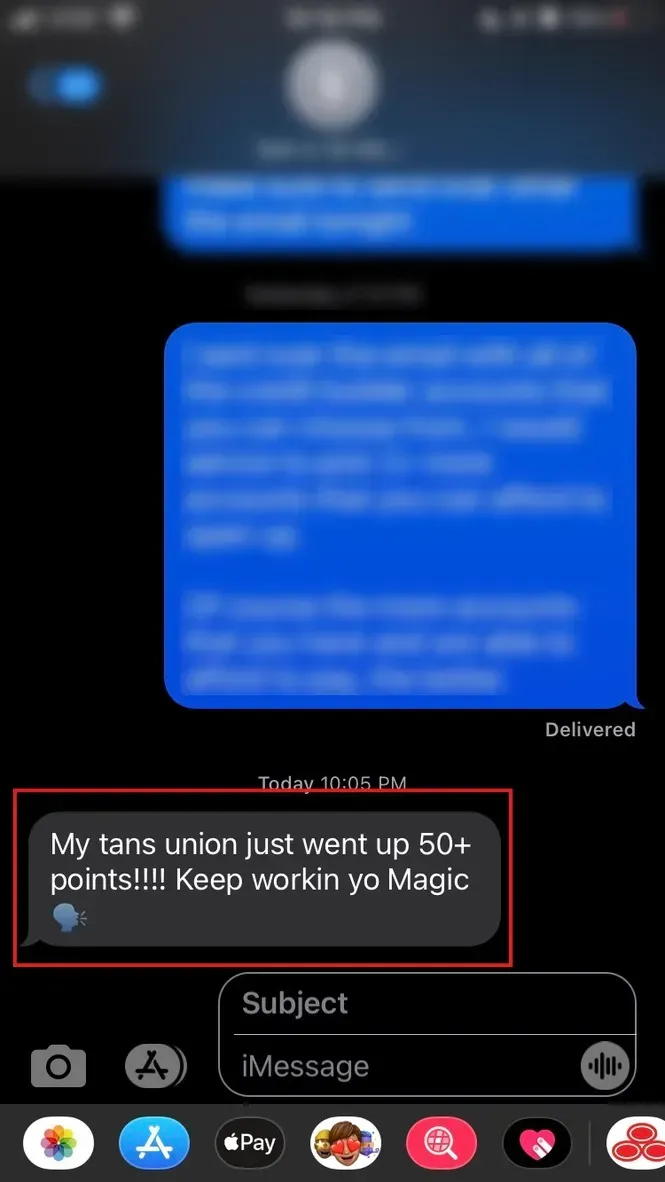
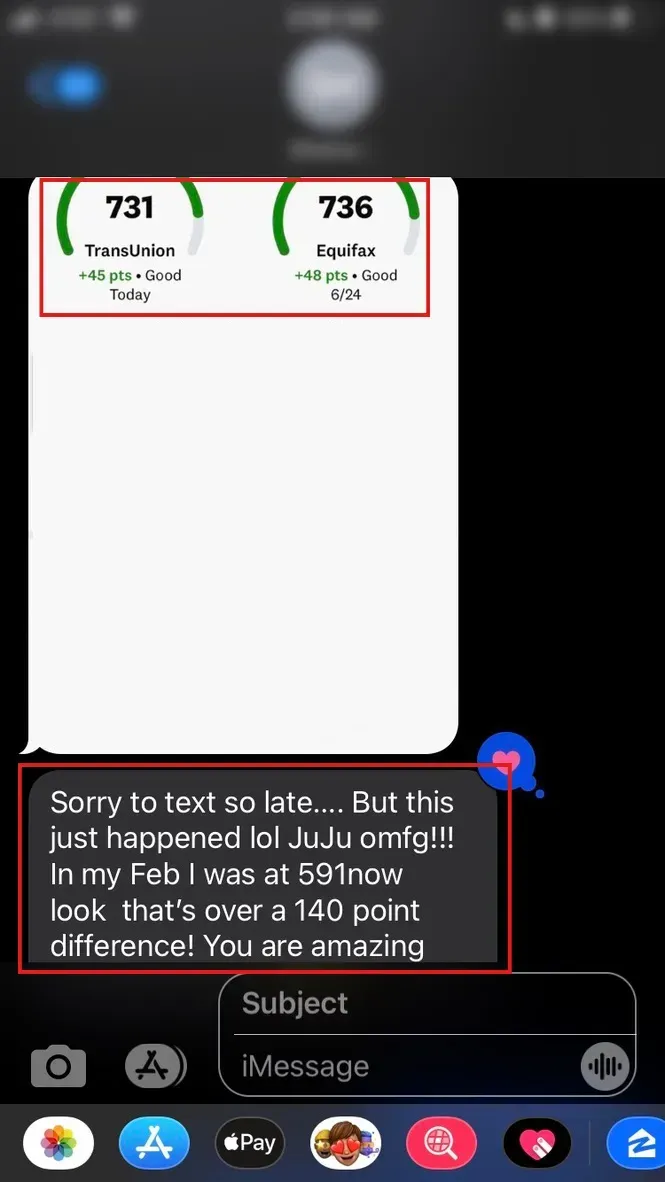
Real People. Real Results.
See what clients have experienced through the TFS Funding process.
TFS gave me clarity around my credit and helped me understand the steps I needed to take next.
John D.
Real Estate Investor
The process was straightforward, professional, and focused on my actual financial goals.
Maria S.
Property Buyer
I finally understood what was happening with my credit and had a clear plan to move forward.
Alex R.
Future Homeowner
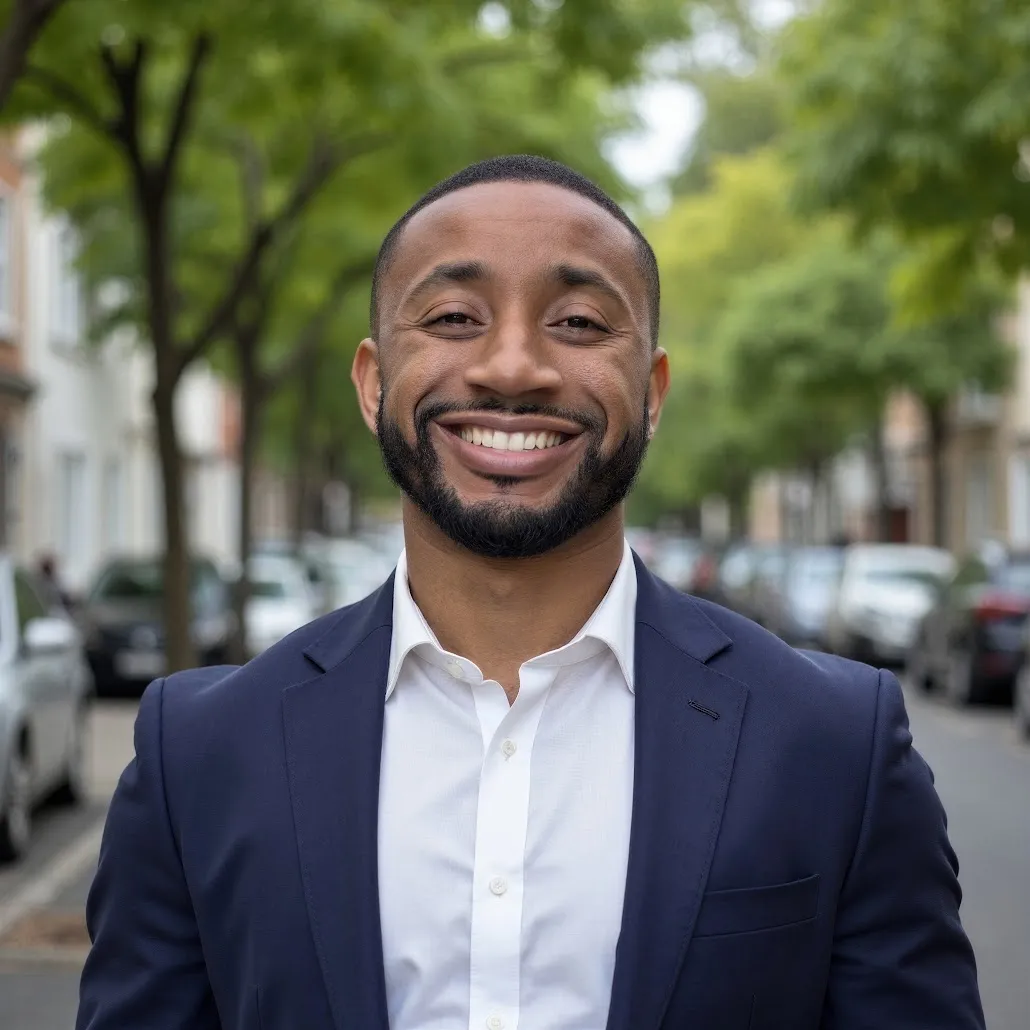
About Me:
I started this company after getting burned by a credit repair company myself. I paid them, trusted them to do what they said they'd do, and six months later found out they hadn't touched my report. No results, no refund, no accountability. It was a hard lesson, but it taught me exactly what I didn't want to become.
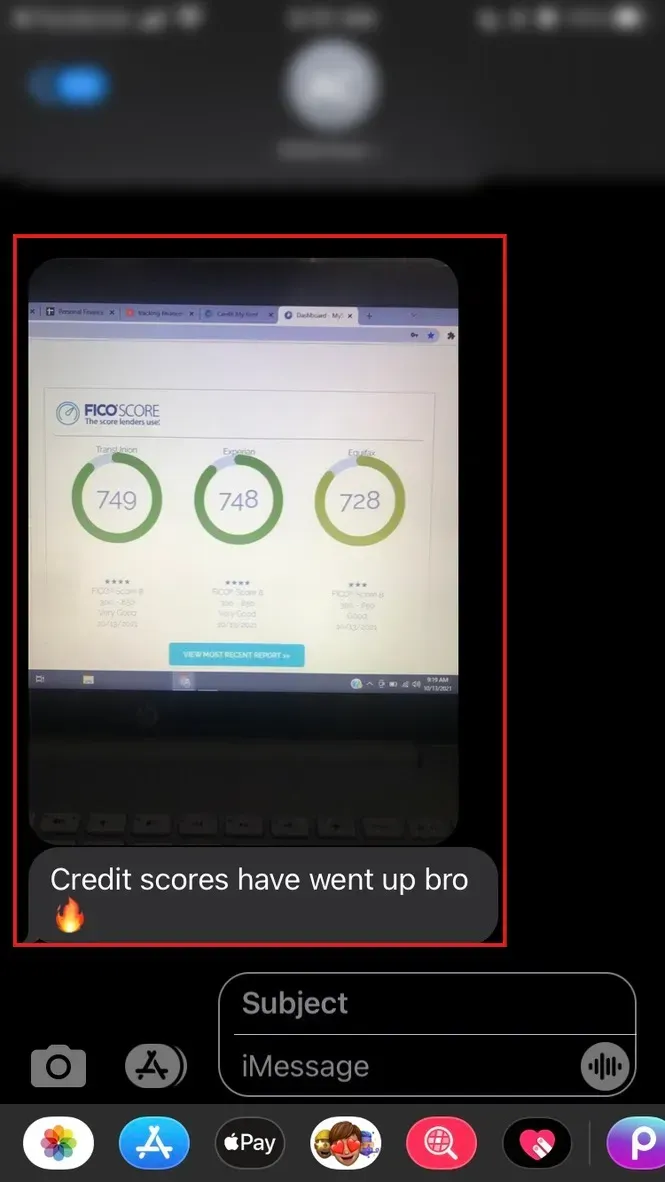
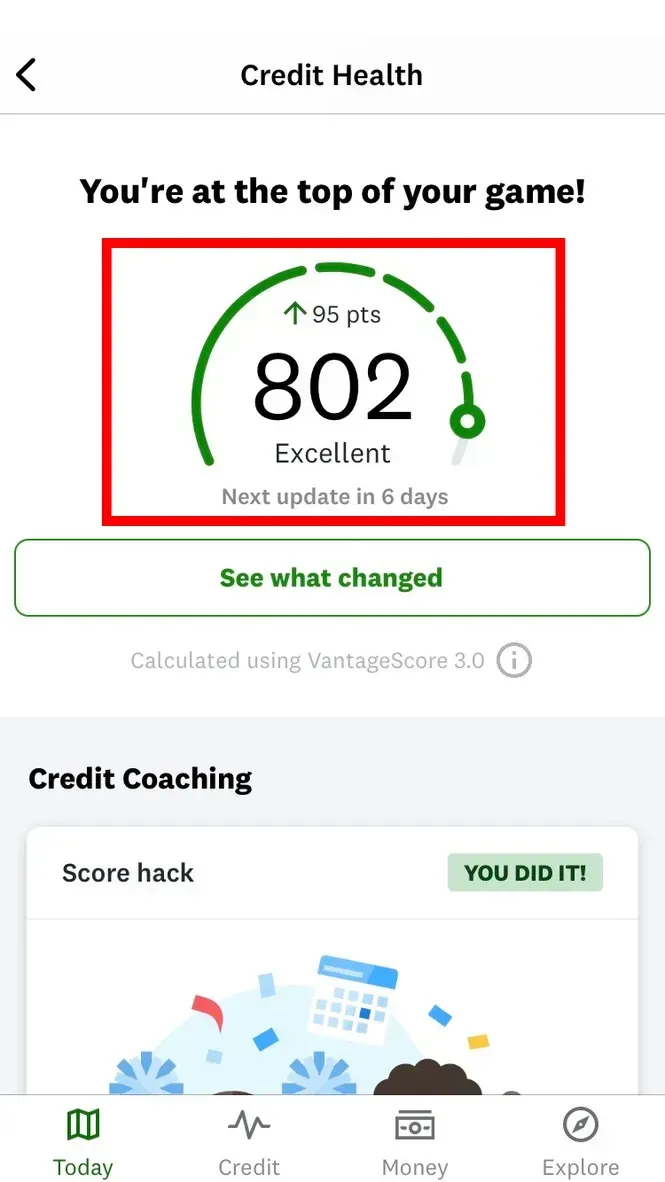
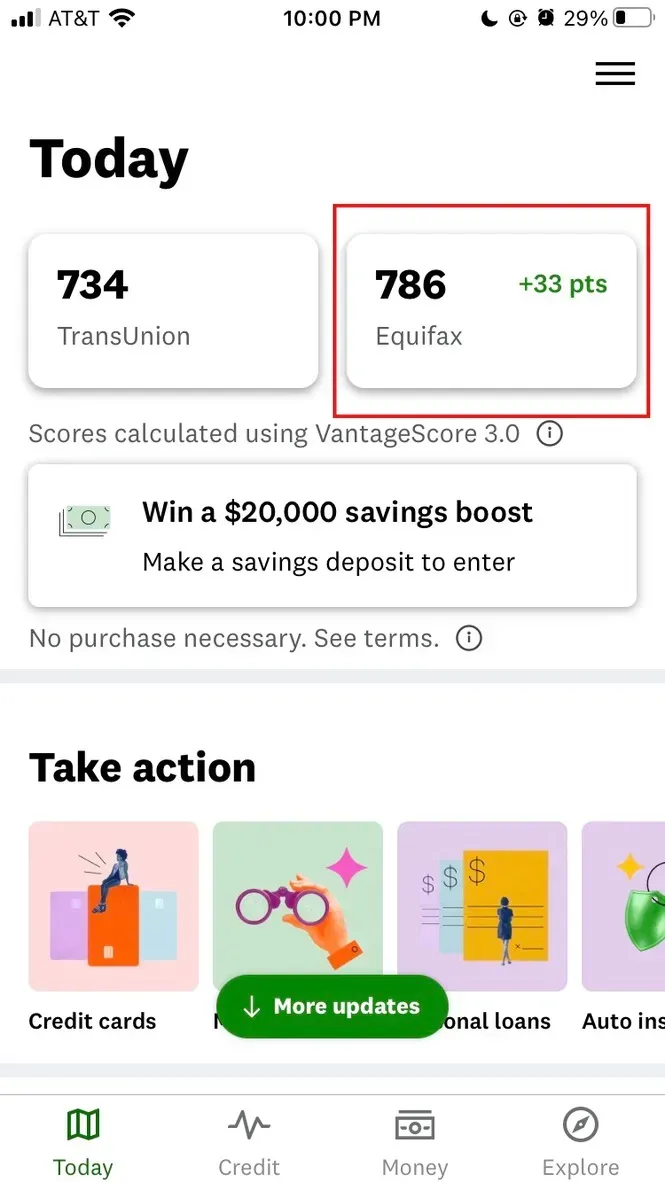
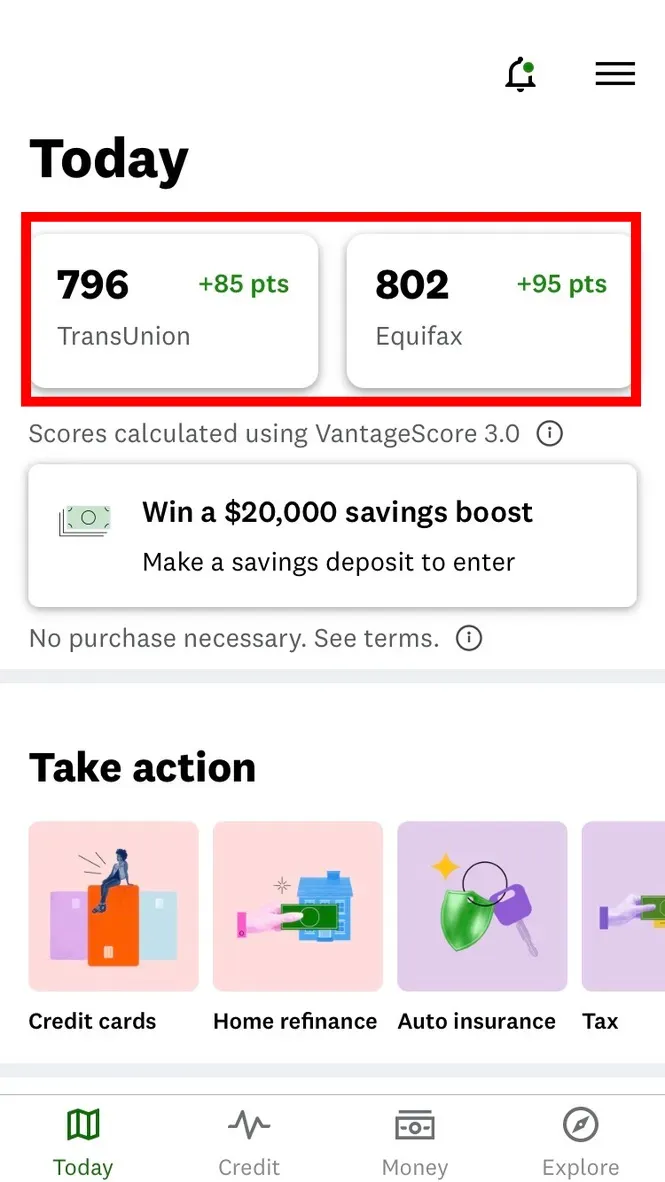
So I learned how to do it myself, and how to do it right. Today, I've helped hundreds of people remove hard inquiries, late payments, charge-offs, and collections, so they can stop waiting and start moving toward what they actually want.
I believe generational wealth starts with property, and property starts with credit. My own grandmother understood that better than anyone I've known. What she built became the foundation for my family, and it's a big part of why I do this work now, helping people put themselves in a position to buy, to invest, and to build something that lasts beyond just them.
Most of my clients don't come to me because they don't know what to do. They come to me because they don't have the time to do it themselves, and they want someone in their corner who's actually going to follow through.
If bad credit's been holding you back from building what you're capable of building, let's put together a real plan and get you there.
BEFORE YOUR CALL
Questions? We've Got Answers.
Here are a few things clients commonly want to know before their strategy session.
What makes this different from other credit repair companies?
Our dispute letters are built on actual case law and FCRA statute research — not AI-generated templates. Every dispute we file is grounded in legal precedent, which means stronger challenges and fewer generic, easily-ignored letters that bureaus brush off.
Who is this for?
First-time homebuyers and anyone working toward mortgage pre-approval who needs their credit in shape — whether that means raising your score, lowering utilization, or cleaning up collections and errors holding your application back.
I've tried fixing my credit myself (or paid another company that didn't work) — can you actually help?
That's exactly who we built this for. Most self-directed or template-based dispute attempts stall because they lack the legal grounding to survive a bureau's automated review. Our approach is different by design.
How does the process start?
We begin with a full credit analysis — pulling your tri-merge report, identifying negative items, and assessing your utilization, account age, and overall mortgage-readiness. From there we build a custom dispute and credit-building roadmap aimed at getting you approval-ready.
How long does credit repair take?
Most clients see measurable movement within 45–60 days (one to two dispute rounds), with fuller results over 3–6 months depending on the complexity of your file. We track every account and every round transparently.
What score do I need to qualify for a mortgage?
It depends on the loan type — conventional, FHA, and other programs all have different minimums. Part of our job is showing you where you stand today and what needs to move to get you into the program that fits you best.
Will you tell me exactly what's being disputed and why?
Yes. You get visibility into your dispute tracker so you can see what's been challenged, the round it's in, and the outcome — no black box.
Do you guarantee results?
We're confident enough in our process that we structure pricing around real outcomes — ask about our upfront and success-fee options during your consultation.
What if my score isn't "mortgage-ready" yet?
That's normal, and it's exactly what the credit repair phase is for. We'll give you a clear picture of where you stand and a timeline for what needs to move before you can get pre-approved.
Can down payment assistance help me buy sooner?
In many cases, yes. We factor lesser-known DPA programs into your overall strategy where they make sense, especially for first-time buyers.
What if I'm not ready to buy but don't want to keep renting long-term?
Rent-to-own paths can bridge the gap for buyers who aren't quite mortgage-ready yet. We can walk you through whether that's a fit for your timeline.
Do you work with my lender/loan officer?
Yes — we're happy to coordinate directly with your lender so your credit work lines up with their underwriting requirements and timeline.
Do you work with clients outside California?
Yes, our process is fully remote and applies nationally.
What do you need from me to get started?
A recent credit report (or authorization to pull one) and a short intake call to map your homebuying timeline and goals.
How do I book a consultation?
Take The First Step
Ready To Find Out What's Possible?
Get a clearer understanding of your credit profile and the next steps toward your goals.
© 2026. All rights reserved.